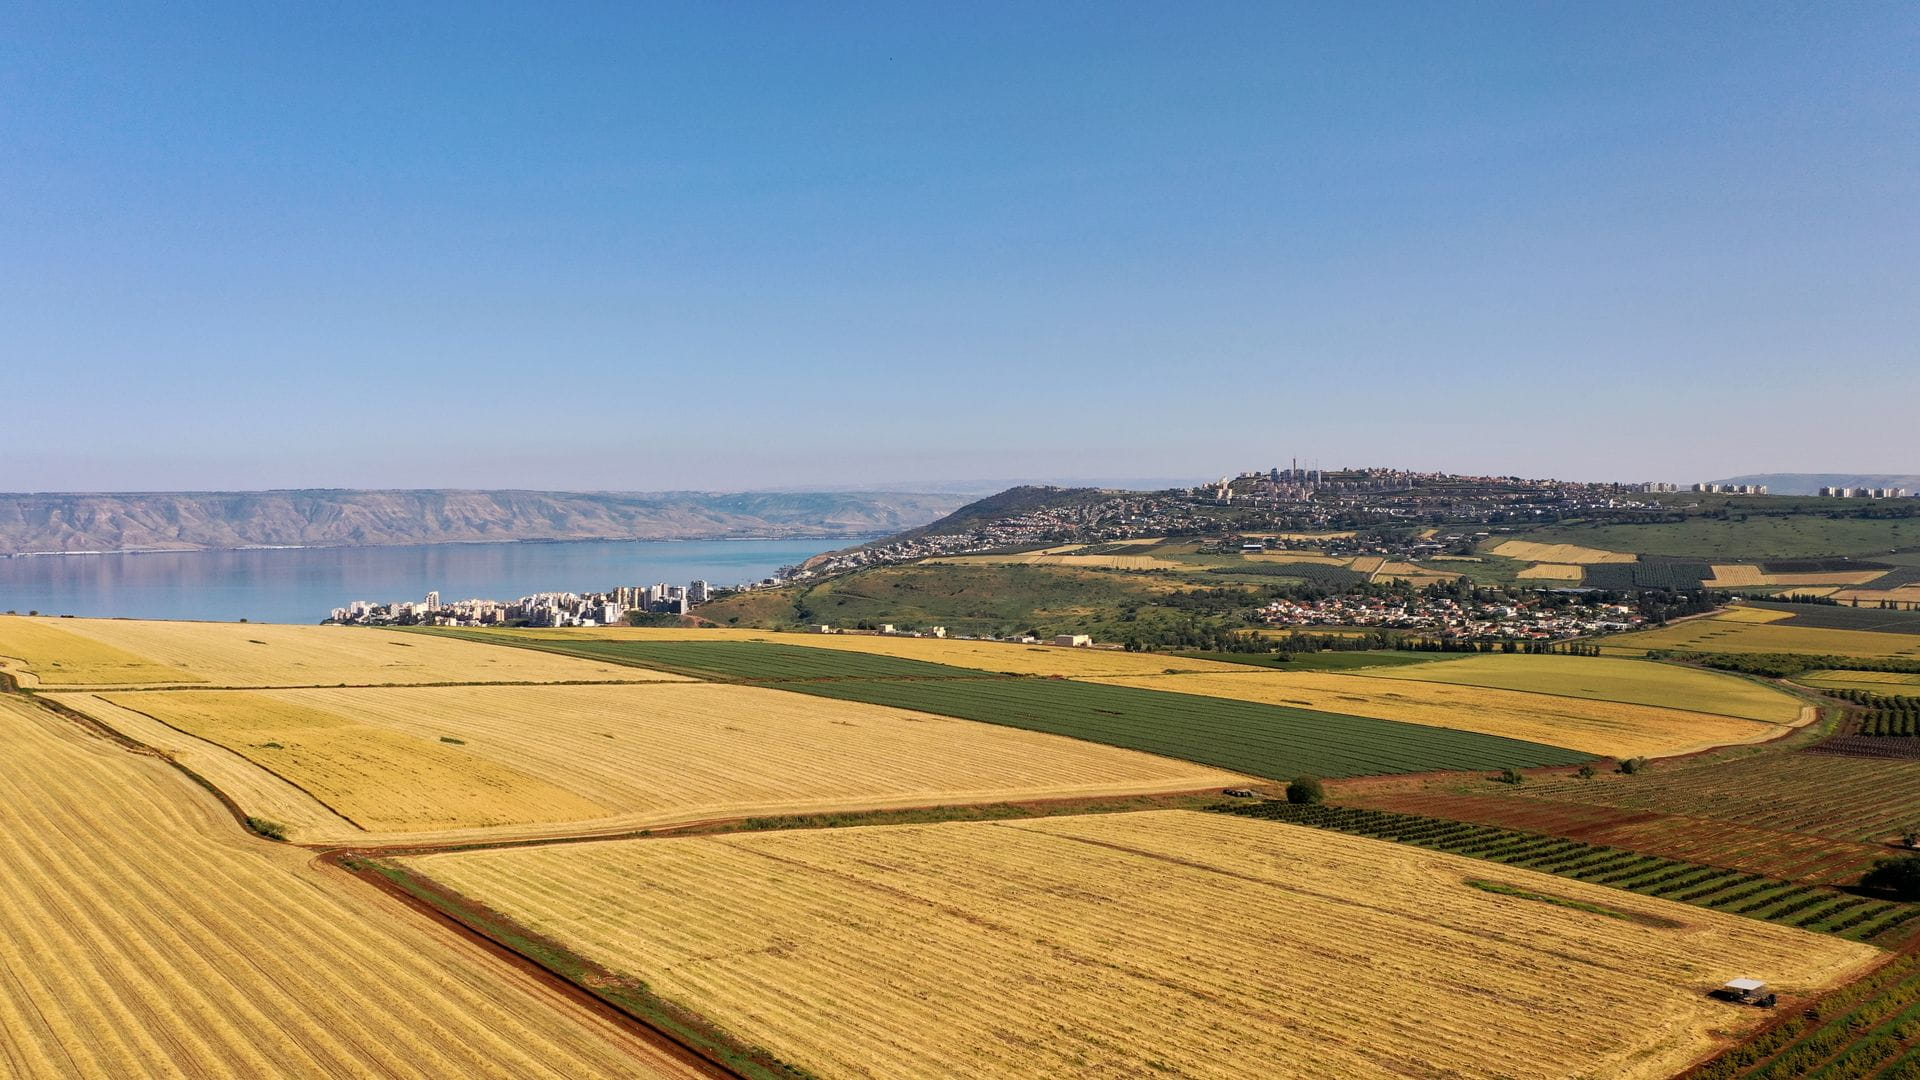
Agricultural land reclassification Israel strategies attract attention because they can create asymmetric outcomes without requiring prime urban entry prices on day one. In committee terms, agricultural land reclassification israel opportunities are compelling only when legal pathway and capital planning are tested together from the beginning. The core idea is simple: acquire land where current use is priced conservatively, then unlock higher value through lawful planning change and disciplined execution. The hard part is not the theory. The hard part is sequencing legal, political, financial, and operational decisions over several years while protecting downside at every checkpoint.
Readers preparing agricultural land reclassification Israel reviews should consult Building an Institutional Execution Model for Private Israeli Real Estate Deals, Risk-Adjusted Returns in Israel: Balancing Growth With Capital Preservation, and Land Banking in Israel: Patience as a Competitive Advantage. What follows concentrates on agricultural land reclassification Israel, not introductory platform mechanics.
Reclassification should also be understood as one component inside a broader platform, not an isolated bet. Teams that combine entitlement pipelines with operating assets generally manage liquidity better across cycles. For reference, the framework in The BRRRR Method Applied to Israeli Real Estate: A Framework for Capital Efficiency shows how capital recycling supports long duration strategies once assets stabilize. In a similar way, land reclassification requires process discipline long before valuation uplift appears on paper.
How planning law turns farmland into an institutional thesis
Israel's land market is heavily influenced by statutory planning designations that define what can be built, when it can be built, and under which infrastructure commitments. A parcel recorded as agricultural land may sit near transport corridors or expanding employment zones, yet still trade at a discount because permitted use remains restricted. Reclassification is the bridge between current designation and future utility, but only when that bridge is supported by law, precedent, and public planning objectives.
Macro and policy context matters at the screening stage. Monetary conditions and credit transmission influence the cost of holding land through entitlement timelines, and those conditions are monitored in publications from the Bank of Israel. Demographic and housing pressure, tracked by the Israel Central Bureau of Statistics, helps investors evaluate whether projected end uses align with durable demand rather than temporary narratives.
The institutional thesis should not start with optimistic residual valuation. It should start with a legal pathway: which committee has jurisdiction, which master plans are relevant, what public interest rationale can support a change, and where similar applications succeeded or failed. Teams that map these factors early can filter quickly and reserve capital for files with genuine planning momentum.
Mapping legal feasibility before paying for optionality
Most avoidable losses occur before acquisition closes. Buyers assume that adjacency to developed neighborhoods implies eventual conversion, then discover later that road access, environmental limits, utility capacity, or policy priorities block progress. To avoid that trap, legal and planning diligence must be completed before final pricing, not after signatures. Paying for optionality is reasonable. Paying for unfounded assumptions is not.
A robust pre-commitment process usually covers title verification, encumbrance analysis, easement status, zoning history, and active objections in the local area. Counsel should confirm who can file, who can object, and what timeline realism looks like under current committee workloads. Planning consultants should provide written probability bands rather than directional optimism. Investment committees can then tie valuation to evidence, with downside cases anchored in current use rather than aspirational use.
Pre-acquisition evidence stack
Institutional teams often require a minimum evidence stack before issuing non-refundable capital. That stack can include a current land registry extract, infrastructure maps, legal memoranda on procedural route, preliminary feedback from qualified planners, and a quantified sensitivity model for time and cost overruns. When teams maintain this discipline, they can walk away from visually compelling parcels that do not meet legal feasibility thresholds. That restraint is frequently the source of long term outperformance.
As opportunities progress, investors can benchmark nearby strategies documented in Value-Add Repositioning in Israel's Urban Core: A Step-by-Step Framework. While urban repositioning differs from raw land conversion, both approaches reward teams that separate operationally controllable upside from purely narrative upside.
Capital design for a multi year entitlement cycle
Reclassification economics are shaped by time as much as by headline uplift. A parcel can eventually secure better designation and still deliver poor returns if carrying costs, legal fees, and opportunity costs consume the spread. Capital design therefore needs to reflect timeline uncertainty from the start. Equity should be phased by milestone, reserve policies should be explicit, and debt should be used only when visibility supports it.
Base case models should include realistic assumptions for committee cadence, revisions, consultant costs, and inflation in professional services. Downside models should test delays caused by objections, infrastructure conditions, and policy shifts at municipal or district level. Global context from the OECD economic snapshot on Israel and the IMF country page for Israel can support macro scenarios for rates, growth, and financing appetite during long holding periods.
Portfolio construction also matters. Teams that allocate all dry powder to entitlement plays can become forced sellers if timelines extend. Balanced programs pair reclassification assets with income producing holdings, creating internal liquidity that protects strategic patience. For institutional allocators, this integration is often discussed alongside cross pillar capital allocation patterns in How Family Offices Are Allocating Capital to Israeli Real Estate.
Structuring reserves and decision gates
One practical method is to divide each project into decision gates with preapproved funding limits: acquisition, filing preparation, committee review, post-review revisions, and monetization. Releasing capital only after objective deliverables reduces escalation by optimism. It also creates cleaner governance records for investment committees and limited partners who need transparent explanations for timeline drift or scope change.
Execution discipline during committee and district approvals
After filing, the value driver becomes execution quality. Many teams underestimate how much coordination is required among lawyers, planners, engineers, transport specialists, and municipal stakeholders. A technically strong application can still stall if communication is inconsistent or if revisions are slow. Program management must be treated as a core competency, with clear accountability and calendar control.
At this stage, information hygiene is critical. Every submission version, official response, required amendment, and consultant opinion should be stored in a structured data room. That archive allows faster reaction when committee questions arise and gives capital partners confidence that the process is being managed rather than merely observed. It also improves handover quality if ownership structures change during the hold period.
Stakeholder mapping should continue throughout review cycles. Neighbor groups, infrastructure agencies, and local authorities may influence conditions even when they are not direct counterparties. Teams that engage these stakeholders with factual preparation and realistic timelines usually reduce surprise friction. Teams that rely on last minute persuasion often face delay multipliers that can distort project level returns.
For ongoing market perspective while files progress, investors can track implementation insights in the Smart Strategies archive and operational updates on the Blog. Consistent learning loops help teams refine assumptions before the next acquisition cycle.
Exit pathways after designation changes
Successful reclassification creates options, not obligations. Once designation improves, owners can pursue direct sale, joint venture development, phased parcel sales, or partial refinancing against de-risked value. The best route depends on balance sheet goals, operating capacity, and market liquidity at the time of decision. A strong process compares options under current conditions instead of defaulting to the strategy imagined at acquisition.
Direct sale can crystallize gains quickly and recycle equity into new opportunities, but it may leave long tail development value for the next owner. Development can capture more upside, yet it introduces construction, leasing, and delivery risk that may not fit every mandate. Joint venture structures can balance both objectives when partner alignment and governance are clearly documented from inception.
Refinancing is sometimes overlooked in land strategies because cash flow is limited before development, but post-reclassification debt can still play a role in portfolio liquidity planning when lenders accept revised risk profiles. Teams should test covenant resilience and refinancing costs before depending on this route. Institutional groups that compare all paths with discipline generally avoid forced decisions at moments of weaker market sentiment.
Governance standards for repeatable reclassification programs
The biggest difference between sporadic wins and durable performance is governance. Repeatable programs define eligibility criteria, diligence standards, approval rights, and reporting templates before opportunities are sourced. They also set explicit stop loss rules for files that lose feasibility due to policy change or unresolved legal obstacles. Without these controls, reclassification pipelines become collections of hopeful stories. With them, pipelines become allocatable strategies.
Quarterly reporting should track metrics that reveal execution health: months in each planning stage, variance versus budgeted professional fees, probability revisions by independent advisors, and expected liquidity windows under base and downside cases. Presenting these metrics alongside operating asset performance gives committees a complete view of risk concentration and capital lockup.
Governance also includes onboarding and communication discipline. New stakeholders should review core policies through the FAQ, while platform context for country strategy is centralized on the Foundation Israel. These resources do not replace legal advice, but they align participants around process standards that reduce avoidable execution error.
Used thoughtfully, agricultural land reclassification in Israel can deliver outsized returns because it rewards structured patience, legal rigor, and operational control at moments when many investors focus only on near term yield. The opportunity remains underused precisely because it is demanding. For institutions willing to run it as a governed program, that complexity can become an enduring edge.
Timeless Value. Perpetual Legacy.