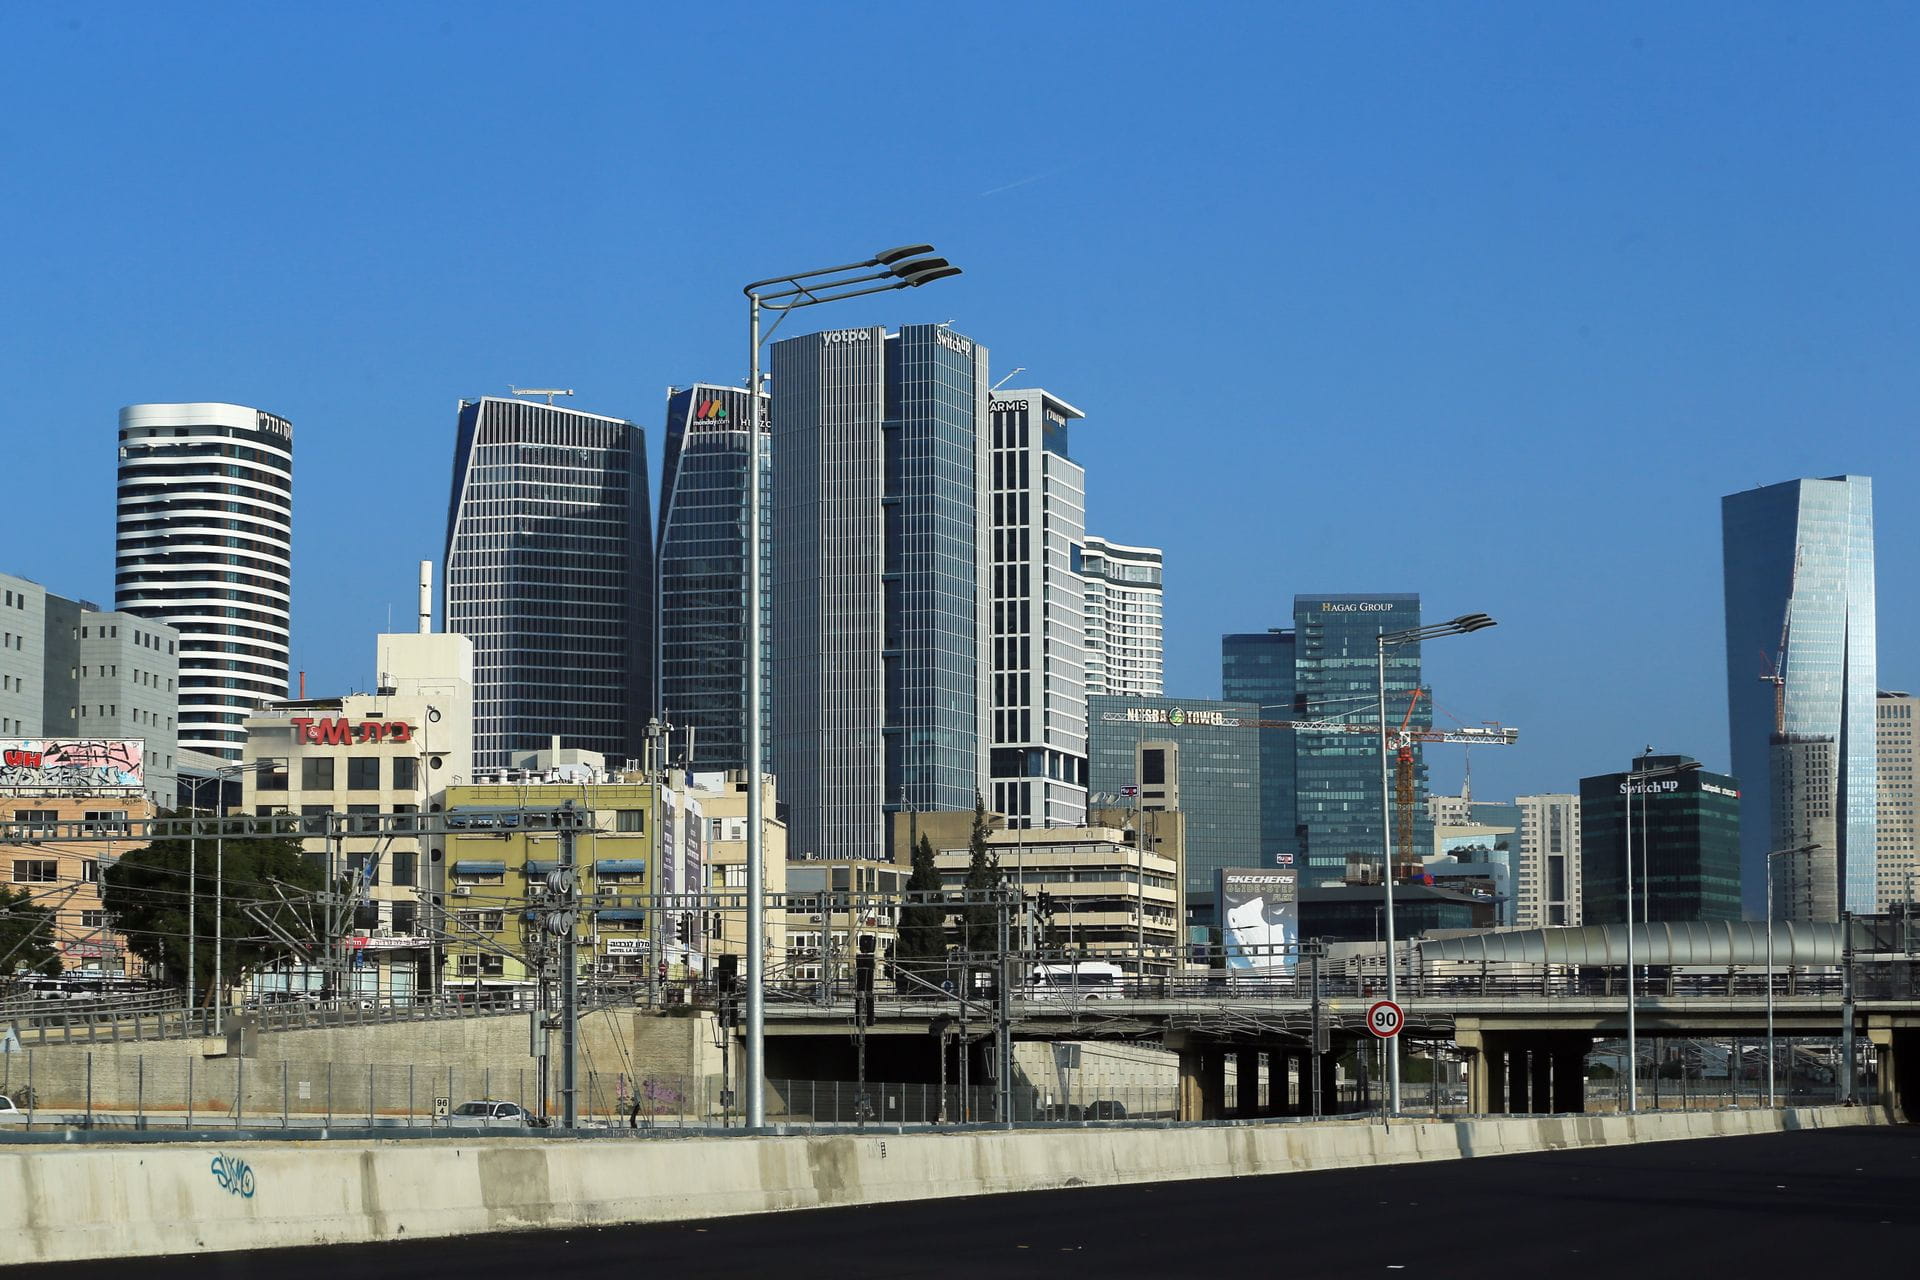
In Israel, many of the strongest real estate opportunities are discussed and priced before they ever appear on listing portals. Owners often prefer private conversations, selective outreach, and direct negotiation with groups that can demonstrate certainty of execution. In a market where quality assets are tightly held and transaction velocity can change quickly, broad exposure is often the final stage of a process, not the first one.
Start with Capital Recycling Strategies for Long-Term Israeli Real Estate Portfolios for same-category context, then Due Diligence Frameworks Every Serious Israeli Property Investor Should Master for same-category context. What follows concentrates on off-market real estate sourcing Israel, not introductory platform mechanics.
That approach requires governance, not improvisation. A disciplined off-market program combines sourcing architecture, underwriting standards, legal controls, and post-closing operating discipline. It also links acquisition activity to a broader portfolio plan. Related frameworks on The BRRRR Method Applied to Israeli Real Estate: A Framework for Capital Efficiency and Agricultural Land Reclassification: An Underused Path to Outsized Returns show how sourcing decisions can support long-duration strategy when execution standards are consistent.
Why Visibility Gaps Persist in Israeli Deal Flow
Supply pressure in central districts is only one part of the story. Israel's ownership structure, planning complexity, and relationship-driven business culture all contribute to an information environment where private channels remain influential. Many owners have little incentive to run open auctions unless they need immediate liquidity. Others want confidentiality around financing, family holdings, or future business plans. As a result, public listings can represent assets that are already widely shopped, while earlier-stage opportunities circulate through trusted intermediaries.
Macro indicators reinforce this pattern. Monetary policy updates and credit conditions from the Bank of Israel shape lender appetite and borrower flexibility, which in turn affects when sellers decide to transact. Demographic and housing data from the Israel Central Bureau of Statistics also point to persistent demand pressure in major employment corridors. In this setting, timing and certainty often command as much pricing power as headline valuation metrics.
Global allocators tracking allocation risk can add context through the OECD's Israel coverage and IMF country material at imf.org. These references do not replace asset-level diligence, but they do help committees frame refinancing assumptions, tenant demand durability, and downside scenarios. In practice, teams that combine macro awareness with street-level sourcing intelligence are better positioned to identify mispriced or under-processed opportunities before competition intensifies.
Building Proprietary Access Before a Deal Is Public
Proprietary access is usually a byproduct of process quality, not personal charisma. High-performing teams map ownership clusters, lender relationships, municipal workflows, and broker incentives by micro-market, then maintain regular non-transactional contact. Coverage routines include periodic outreach to owners, structured follow-up with lenders, and joint review meetings with legal and planning advisors. Over time, this creates a reputation for preparedness and discretion, both of which are decisive when a seller wants a direct conversation instead of a public campaign.
Operational detail: Building Proprietary Access Before a Deal Is Public
The sourcing engine should be segmented by objective. One lane targets income-producing assets where modernization, lease restructuring, or management upgrades can create near-term value. A second lane tracks transitional assets with entitlement or physical complexity that less prepared buyers avoid. A third lane monitors motivated situations tied to refinancing pressure, partnership disputes, or succession events. Teams with family office or multi-generational mandates often align these lanes with governance frameworks similar to those outlined in How Family Offices Are Allocating Capital to Israeli Real Estate.
Institutional continuity matters as much as first contact. Every inbound lead should be captured in a common pipeline taxonomy with explicit status definitions, decision owners, and response times. Data quality should support committee-level analysis, including source reliability, diligence milestones, and expected conversion probability. Without this structure, sourcing becomes anecdotal and difficult to scale. With it, investment leadership can compare channels, rebalance team capacity, and refine where relationship capital is generating the highest risk-adjusted opportunity flow.
Underwriting Off-Market Opportunities With Institutional Discipline
Off-market does not mean lightly vetted. If anything, private sourcing increases the need for rigorous early-stage screens because less standardized information is available at initial contact. Minimum requirements should include title verification, encumbrance review, tax and levy mapping, and a documented legal path to intended use. Investment teams should define non-negotiable red flags in advance so that momentum does not override discipline once bilateral talks begin to accelerate.
Operational underwriting should be built around verifiable cash flow and executable business plans. Where value creation relies on renovation, density optimization, or tenant repositioning, assumptions must be tied to realistic permitting timelines and contractor capacity. Where strategy includes optionality in peripheral locations, teams should stress-test hold costs and timeline variance. The same principle appears in Agricultural Land Reclassification: An Underused Path to Outsized Returns: value is created through managed process execution, not by relying on optimistic headline scenarios.
Capital structure planning should begin before a letter of intent is signed. Debt provider dialogue, covenant sensitivity analysis, and refinancing feasibility all influence entry price discipline. For managers that deploy recycling frameworks, integration with acquisition underwriting is essential, as discussed in The BRRRR Method Applied to Israeli Real Estate: A Framework for Capital Efficiency. The goal is to avoid a mismatch between what can be purchased and what can be stabilized, financed, and held under institutional reporting standards.
Negotiation Design in a Thinly Traded Environment
In markets with constrained supply, negotiation outcomes are often determined by process architecture rather than headline pricing alone. Sellers and counterparties evaluate certainty, confidentiality, and timeline credibility alongside valuation. Institutional buyers can improve outcomes by presenting concise decision pathways, pre-aligned advisors, and clear condition precedent language. This reduces execution anxiety for the seller and increases the likelihood of exclusive dialogue, especially when multiple interested parties are circling without equivalent readiness.
Committee checklist: Negotiation Design in a Thinly Traded Environment
Term sheets should be structured to preserve optionality while signaling commitment. Milestone-based diligence periods, transparent information request schedules, and predefined resolution mechanisms for title or planning issues can keep bilateral negotiations productive. Teams should avoid over-engineering clauses that create friction without reducing core risk. In most cases, a focused structure that balances speed with defensible downside protection will outperform both aggressive overreach and passive compliance with seller-friendly drafts.
Execution Controls From LOI to Closing
Once exclusivity is established, the primary risk is execution slippage. Committees should require a single integrated timeline that combines legal diligence, technical surveys, financing workstreams, and municipal checkpoints. Critical dependencies should be explicit, with accountable owners and escalation protocols. Weekly operating reviews are not bureaucratic overhead in this context. They are the mechanism that protects transaction integrity when multiple specialists are moving in parallel under compressed timelines.
Documentation standards should be designed for both investment governance and future financing events. Every material assumption, filing, and budget revision should be stored in a searchable data room indexed to decision points. This supports cleaner handoff to asset management and strengthens lender confidence at refinance or recapitalization stages. Teams that want ongoing implementation guidance can monitor updates through the Blog, while stakeholder onboarding and policy clarifications are centralized in the FAQ.
Portfolio Integration and Pipeline Management
Off-market sourcing creates durable advantage only when it is integrated into portfolio construction, not treated as a standalone acquisition tactic. Investment committees should review sourced opportunities against concentration limits, liquidity buffers, and operating bandwidth before approving growth targets. A healthy pipeline is defined by quality and fit, not by volume alone. Portfolio-level discipline ensures that sourcing success does not unintentionally increase exposure to correlated regulatory, geographic, or financing risks.
Institutional teams should also treat knowledge compounding as a measurable asset. Post-mortems on won and lost situations can improve channel selection, underwriting speed, and negotiation effectiveness over time. Publishing and reviewing codified practices across teams strengthens continuity when personnel change. For broader strategy context, decision-makers can track related perspectives in the Smart Strategies archive and on the Foundation Israel.
When designed as a repeatable operating system, private sourcing can deliver better entry basis, stronger process control, and more predictable portfolio outcomes in Israel's constrained market environment. The edge does not come from secrecy alone. It comes from prepared teams that combine local intelligence, disciplined underwriting, and execution reliability from first outreach through long-term asset stewardship.
Timeless Value. Perpetual Legacy.