Israeli allocators often confuse breadth with balance. Owning assets in Tel Aviv, Jerusalem, and Haifa does not automatically produce a resilient book if every position shares the same operator, entitlement type, or financing structure. A disciplined diversified real estate portfolio Israel program begins with sleeve level policy: which corridors, property types, and risk bands belong together, and which concentrations require explicit committee approval. The objective is not maximal deal count. It is controlled exposure across core markets where liquidity, demand depth, and institutional execution standards are strongest.
Readers preparing diversified real estate portfolio Israel reviews should consult Controlling Renovation Costs on Israeli Repositioning Projects, Scaling From a Single Israeli Property to an Institutional-Grade Portfolio, and Managing Currency Exposure When Investing in Shekel-Denominated Assets. What follows concentrates on diversified real estate portfolio Israel, not introductory platform mechanics.
Define diversification as sleeve policy, not asset count
Diversification policy should state measurable limits before acquisitions close. Typical bands include geographic corridor, property type, hold period, operator dependency, leverage tier, and entitlement stage. Committees that document limits at mandate level avoid debating whether the fifth office asset in the same district still counts as diversified.
Asset count alone misleads when correlations remain high. Five stabilized multifamily assets managed by one operator can behave like a single position during contractor stress or refinancing pressure. Sleeve policy therefore tracks effective concentration, not only headline property totals.
Investment memos should explain how each proposed acquisition moves the portfolio toward or away from policy bands. Approvals without that context usually produce quiet drift that surfaces only when a macro shock hits every correlated sleeve at once.
Map Israel core markets with evidence discipline
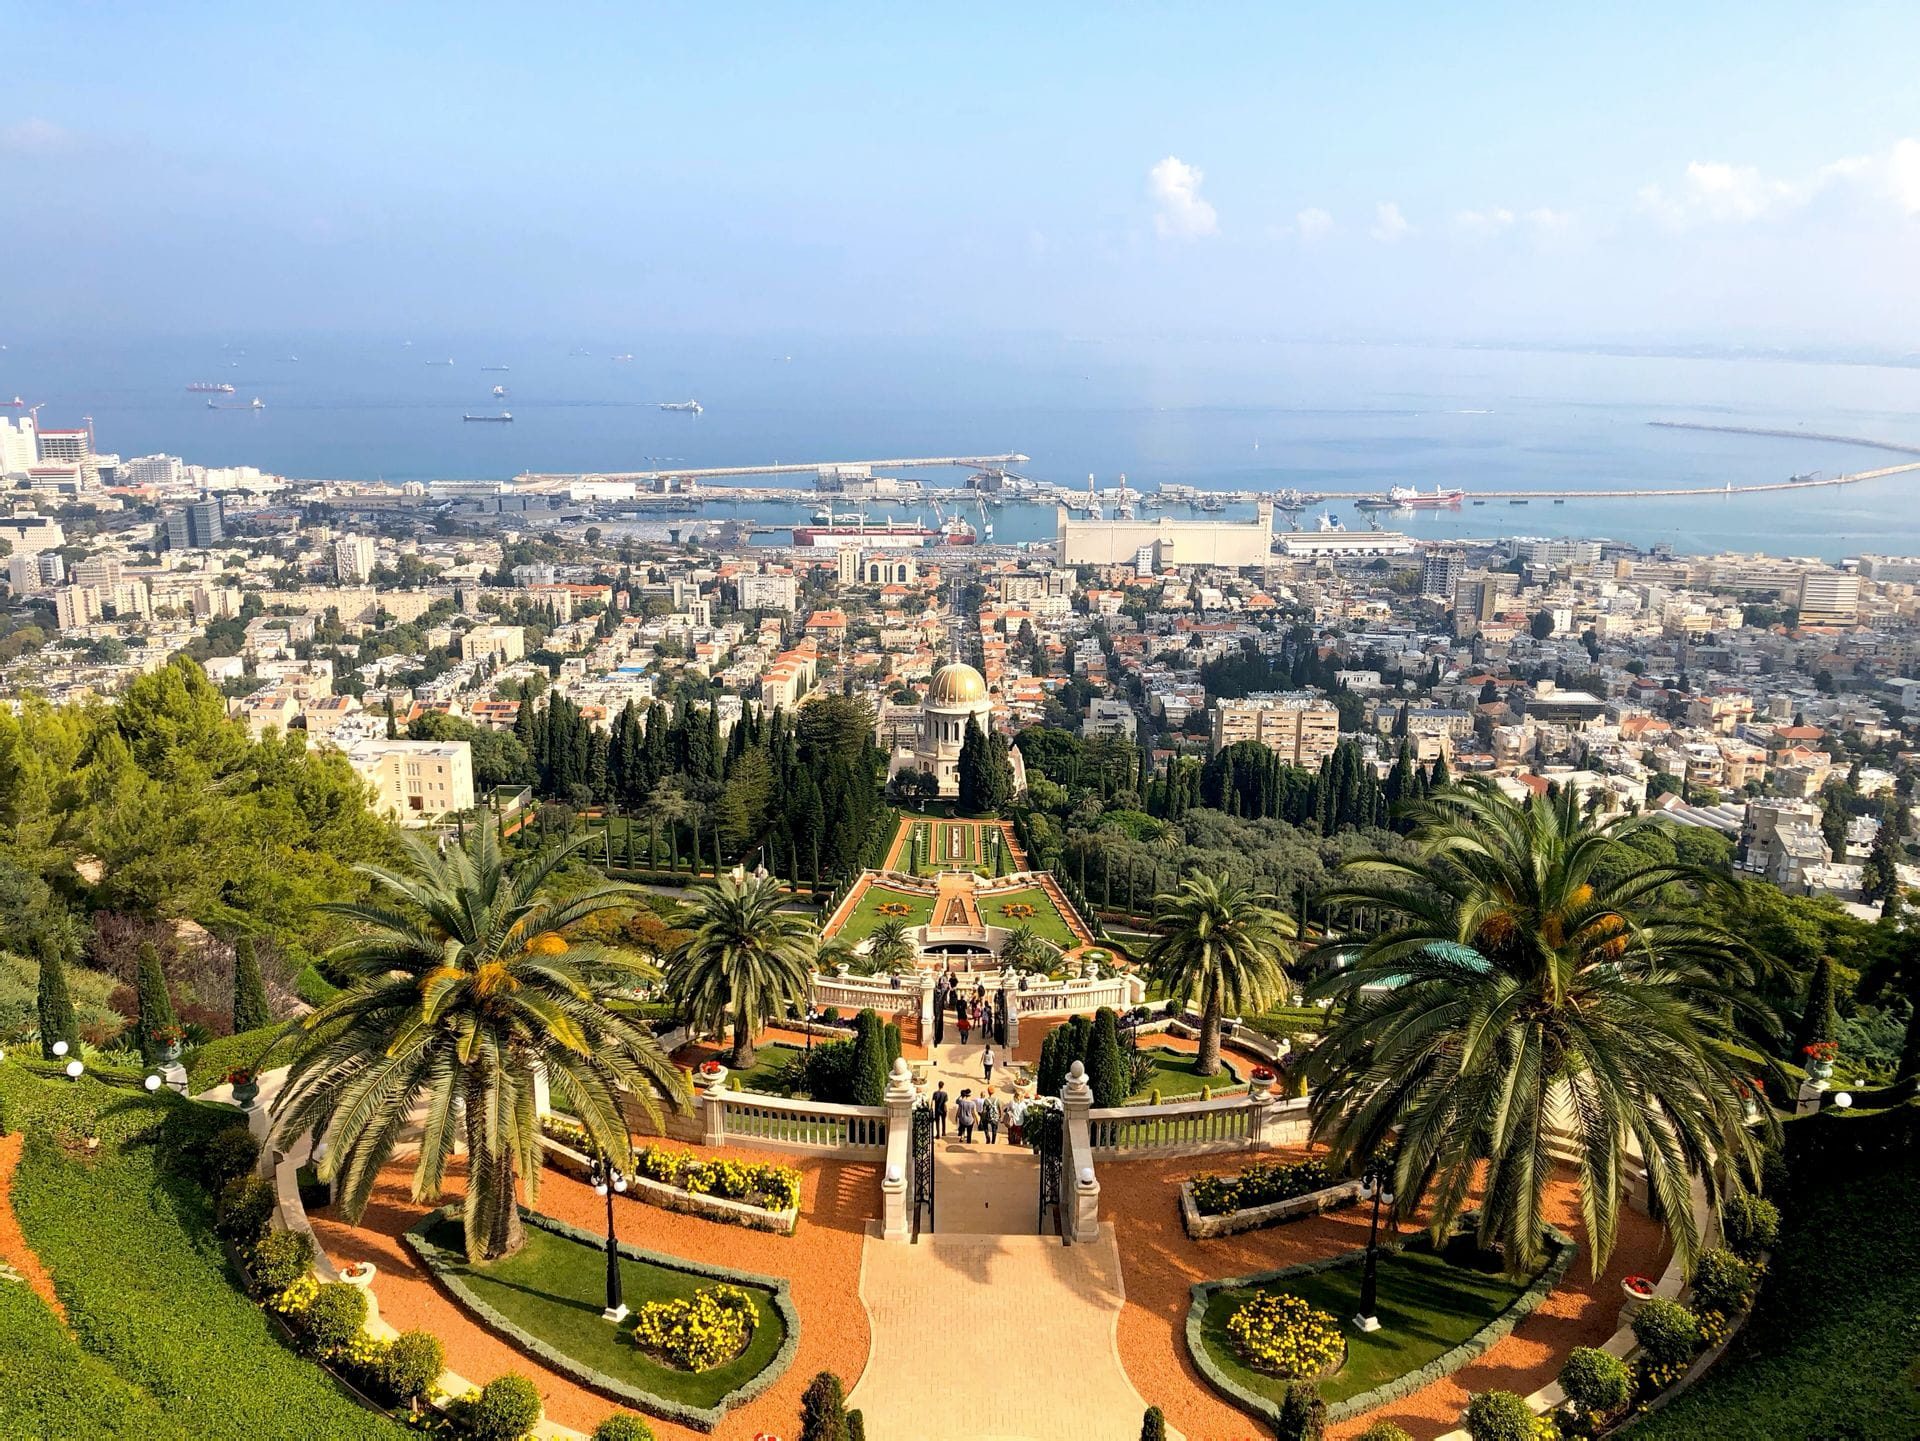
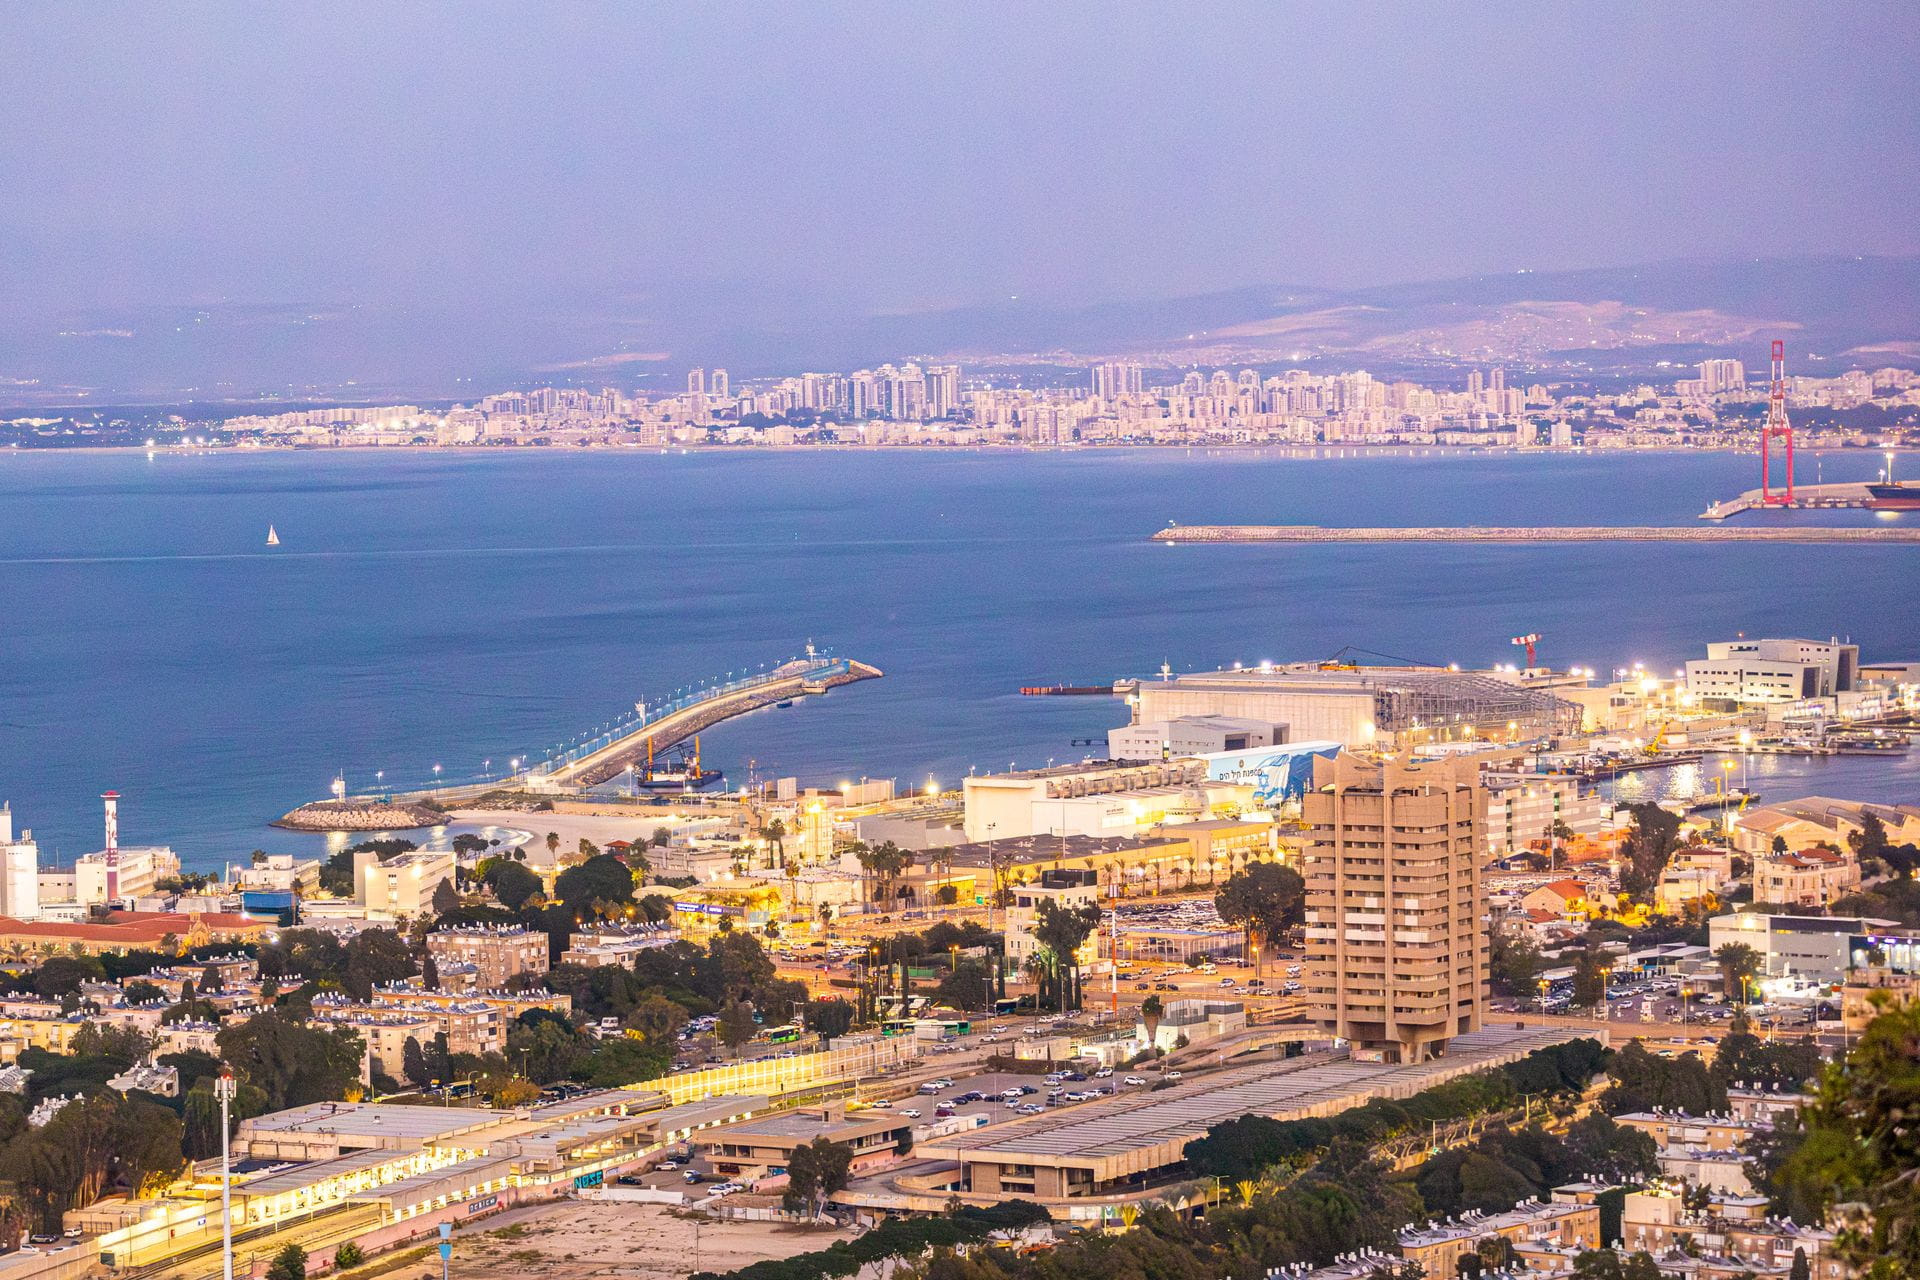
Core markets in Israel combine persistent housing demand, employment anchors, infrastructure investment, and liquid financing access relative to secondary towns. Tel Aviv metropolitan corridors, Jerusalem's mixed use districts, Haifa's port linked employment base, and select inner suburban nodes often qualify, but qualification should be evidence based rather than brand based.
Evidence files should include household formation trends, employment mix, transit and road investment pipelines, and observed transaction depth by property type. Macro housing context from the Israel Central Bureau of Statistics informs demand direction, while district level leasing and sales data still determine whether a specific micro market belongs in a core sleeve.
Committees should revisit core market maps annually. Infrastructure projects, security patterns, and municipal policy shifts can upgrade or downgrade a corridor's role in the portfolio without any single asset failing operationally.
Balance property types and risk sleeves across corridors
Property type balance prevents a portfolio from becoming a single strategy in disguise. Residential income, office, retail with residential upper floors, logistics near urban nodes, and value add repositioning sleeves each carry different cyclical and operational profiles. A core market portfolio can still concentrate risk if every asset depends on the same lease structure or capex profile.
Risk sleeves should pair growth oriented positions with stabilized income anchors. Value add and entitlement heavy assets can deliver upside, but they consume operator attention and liquidity reserves that stabilized assets protect during stressed periods.
Sleeve types committees standardize
Institutional programs often define four reusable sleeves: stabilized income, value add repositioning, entitlement optionality, and land or development inventory awaiting conversion. Each sleeve carries distinct underwriting, reporting cadence, and exit triggers. Standardization helps committees compare new deals against portfolio level targets instead of against the last successful transaction narrative.
Cap rate dynamics across sleeves are developed in Cap Rate Compression in Israel: What It Means for Value-Add Investors, which explains how tightening yields should influence acquisition pacing inside a diversified book.
Integrate capital recycling without concentration drift
Capital recycling can improve returns while quietly increasing concentration if proceeds always redeploy into the same operator or district. Recycling policy should specify where extracted equity may land and which bands require fresh approval after each refinance or sale event.
BRRRR style sequencing helps teams compound equity without liquidating scarce positions, but sequencing must respect diversification limits. A successful recycle into another asset in the same micro market may breach corridor caps even when asset level returns look attractive.
Frameworks for acquisition, improvement, stabilization, and redeployment appear in The BRRRR Method Applied to Israeli Real Estate: A Framework for Capital Efficiency and again when committees compare recycle pacing against sleeve level liquidity targets in the same essay's milestone sections.
Financing conditions published by the Bank of Israel affect how aggressively portfolios can recycle without overleveraging correlated assets during rate transitions.
Align diversification with family office allocation bands
Family offices and institutional allocators often maintain target bands across geography, strategy, and liquidity horizon. Israeli core market sleeves should map cleanly to those bands so quarterly reviews do not become arguments about classification rather than risk.
When offshore capital participates alongside local operators, allocation bands should specify currency exposure, repatriation assumptions, and how Israeli positions rank against other country sleeves. Misalignment between family level policy and asset level execution produces ad hoc acquisitions that look diversified on a property list but concentrated in mandate terms.
Pacing guidance for family office programs appears in How Family Offices Are Allocating Capital to Israeli Real Estate, which pairs liquidity events with allocation targets across market cycles.
Govern correlation risk across operators and districts
Correlation risk rises when multiple assets depend on the same contractor network, municipal relationship, lender package, or security sensitive tenant base. Diversification reviews should include operator maps and vendor overlap analysis, not only geographic spread on a chart.
District level shocks can move correlated assets together even when property types differ. Committees should stress portfolios against combined scenarios: entitlement delay plus financing tightening, or occupancy softness plus capex overrun across assets sharing one renovation program.
Correlation checkpoints before new acquisitions
Before approving a new acquisition, reviewers should confirm the deal does not breach operator, lender, or contractor concentration thresholds. Checkpoints should also flag when an asset introduces a new entitlement type that the portfolio already holds in another district under the same execution team.
Tax and entity structures can create hidden correlation when multiple assets flow through one partnership with shared liability exposure. High level orientation from the Israel Tax Authority frames entity level questions, but transaction counsel still validates how structure affects portfolio level risk reporting.
Make diversification discipline repeatable across cycles
Repeatable diversification uses living policy documents, quarterly concentration reports, recycle approval rules, and post acquisition reviews that compare actual exposure to approved bands. Repeatability prevents each committee meeting from reinventing what diversification means under current market enthusiasm.
Post cycle reviews should capture whether policy bands worked, which correlations appeared despite geographic spread, and whether capital recycling respected limits during competitive acquisition windows. Reviews improve the next mandate revision more than narrative deal summaries do.
Additional portfolio construction notes sit in the Smart Strategies archive. Concentration and mandate questions recur on the FAQ, and corridor level market commentary is updated on the Blog. Integrated platform context for Israeli real estate governance is available at Foundation Israel.
Constructing a diversified real estate portfolio inside Israel's core markets is ultimately a governance product expressed through acquisition pacing, recycling rules, and honest concentration math. Teams that define sleeves before deal flow accelerates preserve mandate integrity across cycles. Teams that treat diversification as a map pin exercise usually discover too late that geography varied while risk stayed in one basket.
Related Foundation reading: Haredi Household Size and Unit Mix: Metrics That Move Headlines.
Timeless Value. Perpetual Legacy.