Tourism capital rarely sits still. Operators and private owners who hold hotels, short-stay apartments, and mixed hospitality stock in Israel watch Greek island and mainland inventory just as closely, looking for moments when relative pricing, occupancy, and airlift favor a rotation of assets or reinvestment. This piece builds a practical supply and demand scorecard so readers can judge when Greek recovery or Israeli coastal strength deserves a reallocation of attention and capital.
Why Capital Shifts Between Greek Islands and Israeli Shores
Both markets sell sun, sea, and cultural density, yet their cycles rarely align perfectly. Greek destinations rebounded after multi-year debt stress with heavy hotel renovation and new branded stock. Israeli coastal cities, especially Tel Aviv and the Mediterranean strip, lean on year-round domestic travel plus inbound business and leisure traffic that reacts quickly to security perceptions and flight connectivity. When one market fills rooms faster or commands higher average daily rates, equity and debt quietly migrate. Foundation tracks these rotations because they reveal where operating leverage and exit multiples can improve without waiting for a full national recovery.
Private owners often hold small portfolios that can be partially liquidated or refinanced. Selling a secondary Greek property after a strong summer and redeploying into Israeli short-stay inventory, or the reverse, becomes rational once the scorecard shows sustained imbalance. The same logic applies to larger funds that rebalance exposure across the Eastern Mediterranean.
Building a Simple Supply and Demand Scorecard
A usable scorecard needs only a handful of observable inputs. On the supply side count completed rooms, rooms under construction, and short-stay units registered on major platforms. On the demand side track overnight stays, average length of stay, and flight seats into the main gateways. Weight each component so no single noisy month dominates. Israeli data can be cross-checked against the Israel Central Bureau of Statistics tourism tables, while Greek figures appear in national tourism barometers and island authority releases.
Assign a simple traffic-light score to each cell: green when demand growth outpaces supply, amber when the two move together, red when new inventory clearly exceeds visitor growth. Recalculate quarterly. The resulting grid shows where pricing power is strongest and where soft occupancy may force discounts. Readers who manage multiple assets can then decide whether to hold, renovate, or rotate.
Core Metrics That Belong on Every Card
Room-nights available versus room-nights sold remains the foundation. Secondary metrics include RevPAR (revenue per available room), length of stay, and the share of domestic versus international guests. Currency movements between the euro and the shekel also matter because they change the relative cost of a holiday for the same traveler. Keep the list short enough that non-experts can update it with public sources.
Greek Inventory Growth After the Debt Years
Greece entered a multi-year renovation wave once bank financing and foreign equity returned. Large island groups and select mainland resorts added branded hotels and upgraded independent properties. That supply response was necessary after years of underinvestment, yet it also created periods when new keys arrived faster than visitor growth. Seasonal peaks still fill most beds, but shoulder seasons can soften quickly if airlift or marketing falters.
Investors comparing the two countries therefore watch Greek construction permits and hotel pipeline announcements as leading indicators. When the pipeline thickens while arrival growth plateaus, the scorecard tilts amber or red for pure leisure assets. That signal often coincides with quieter capital markets in Athens and easier entry pricing for those willing to buy and hold through the next cycle.
Israeli Coastal Demand Drivers and Domestic Resilience
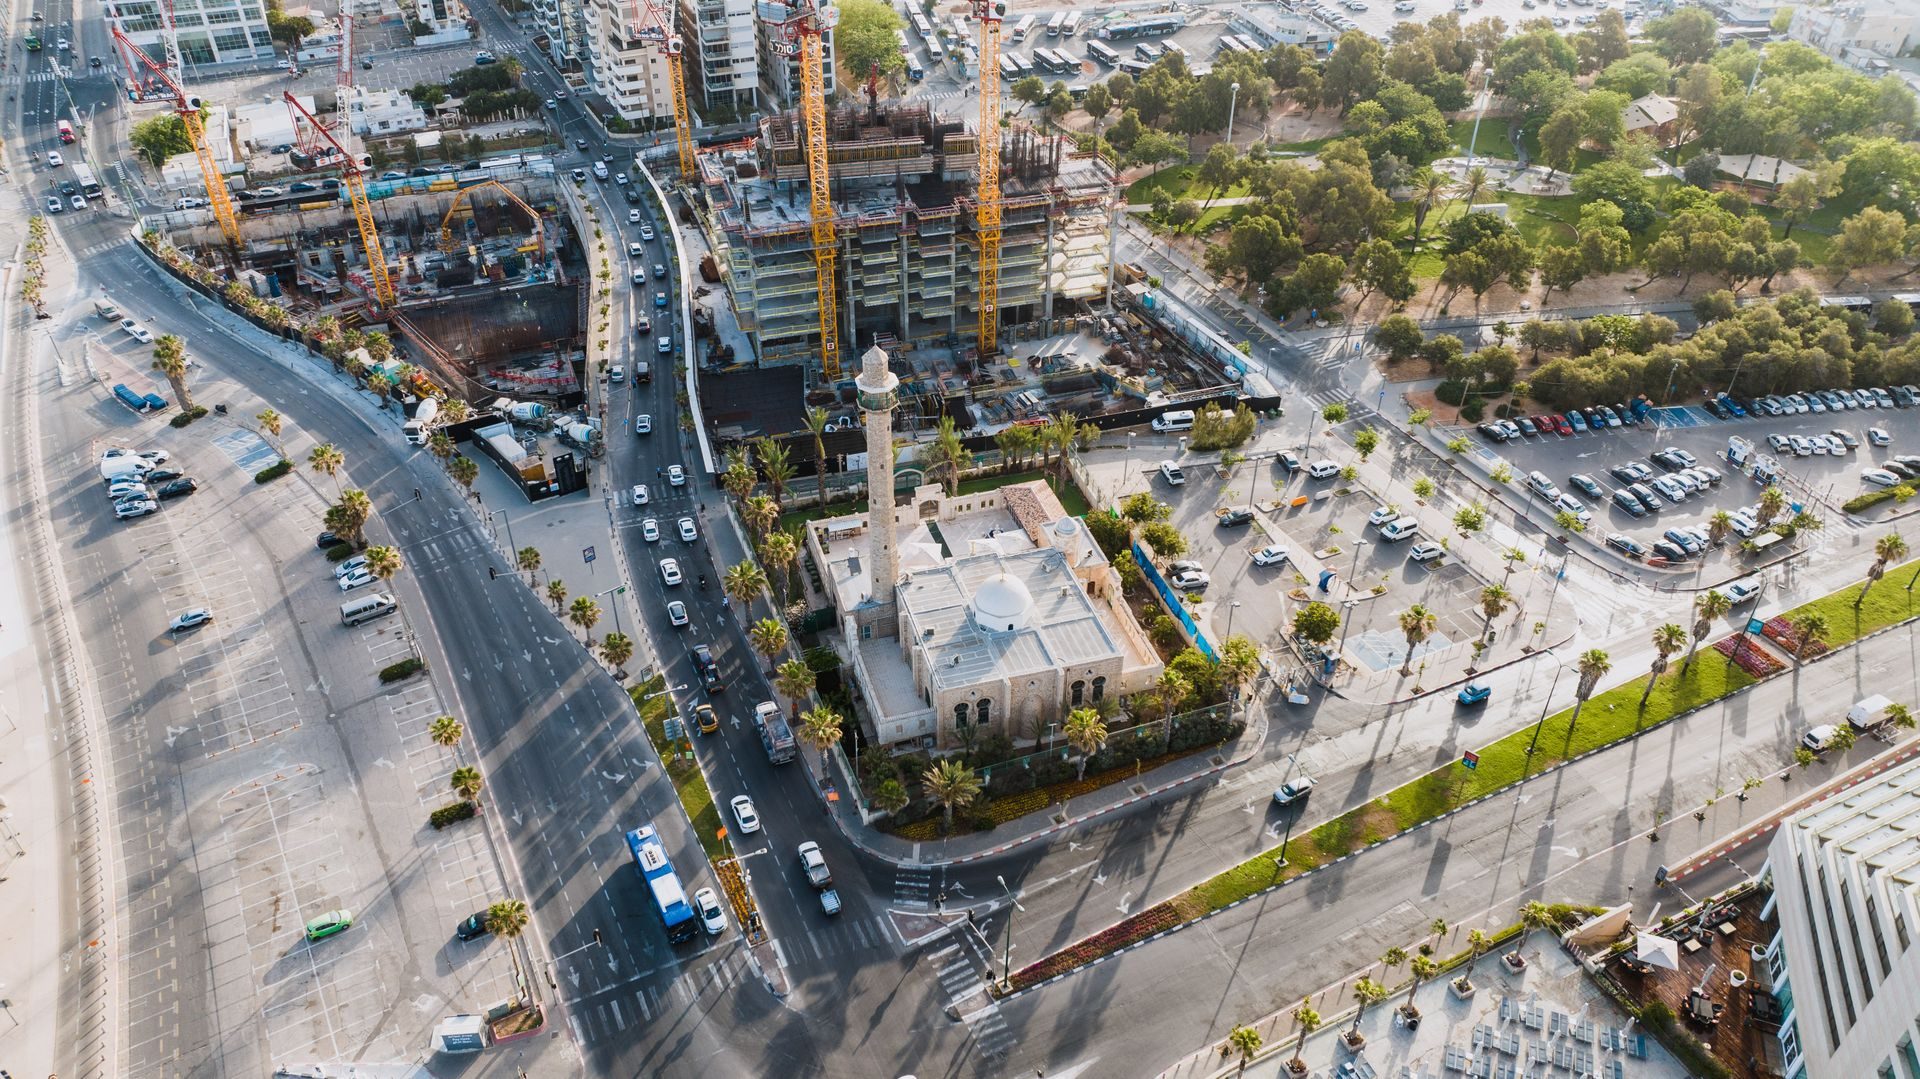
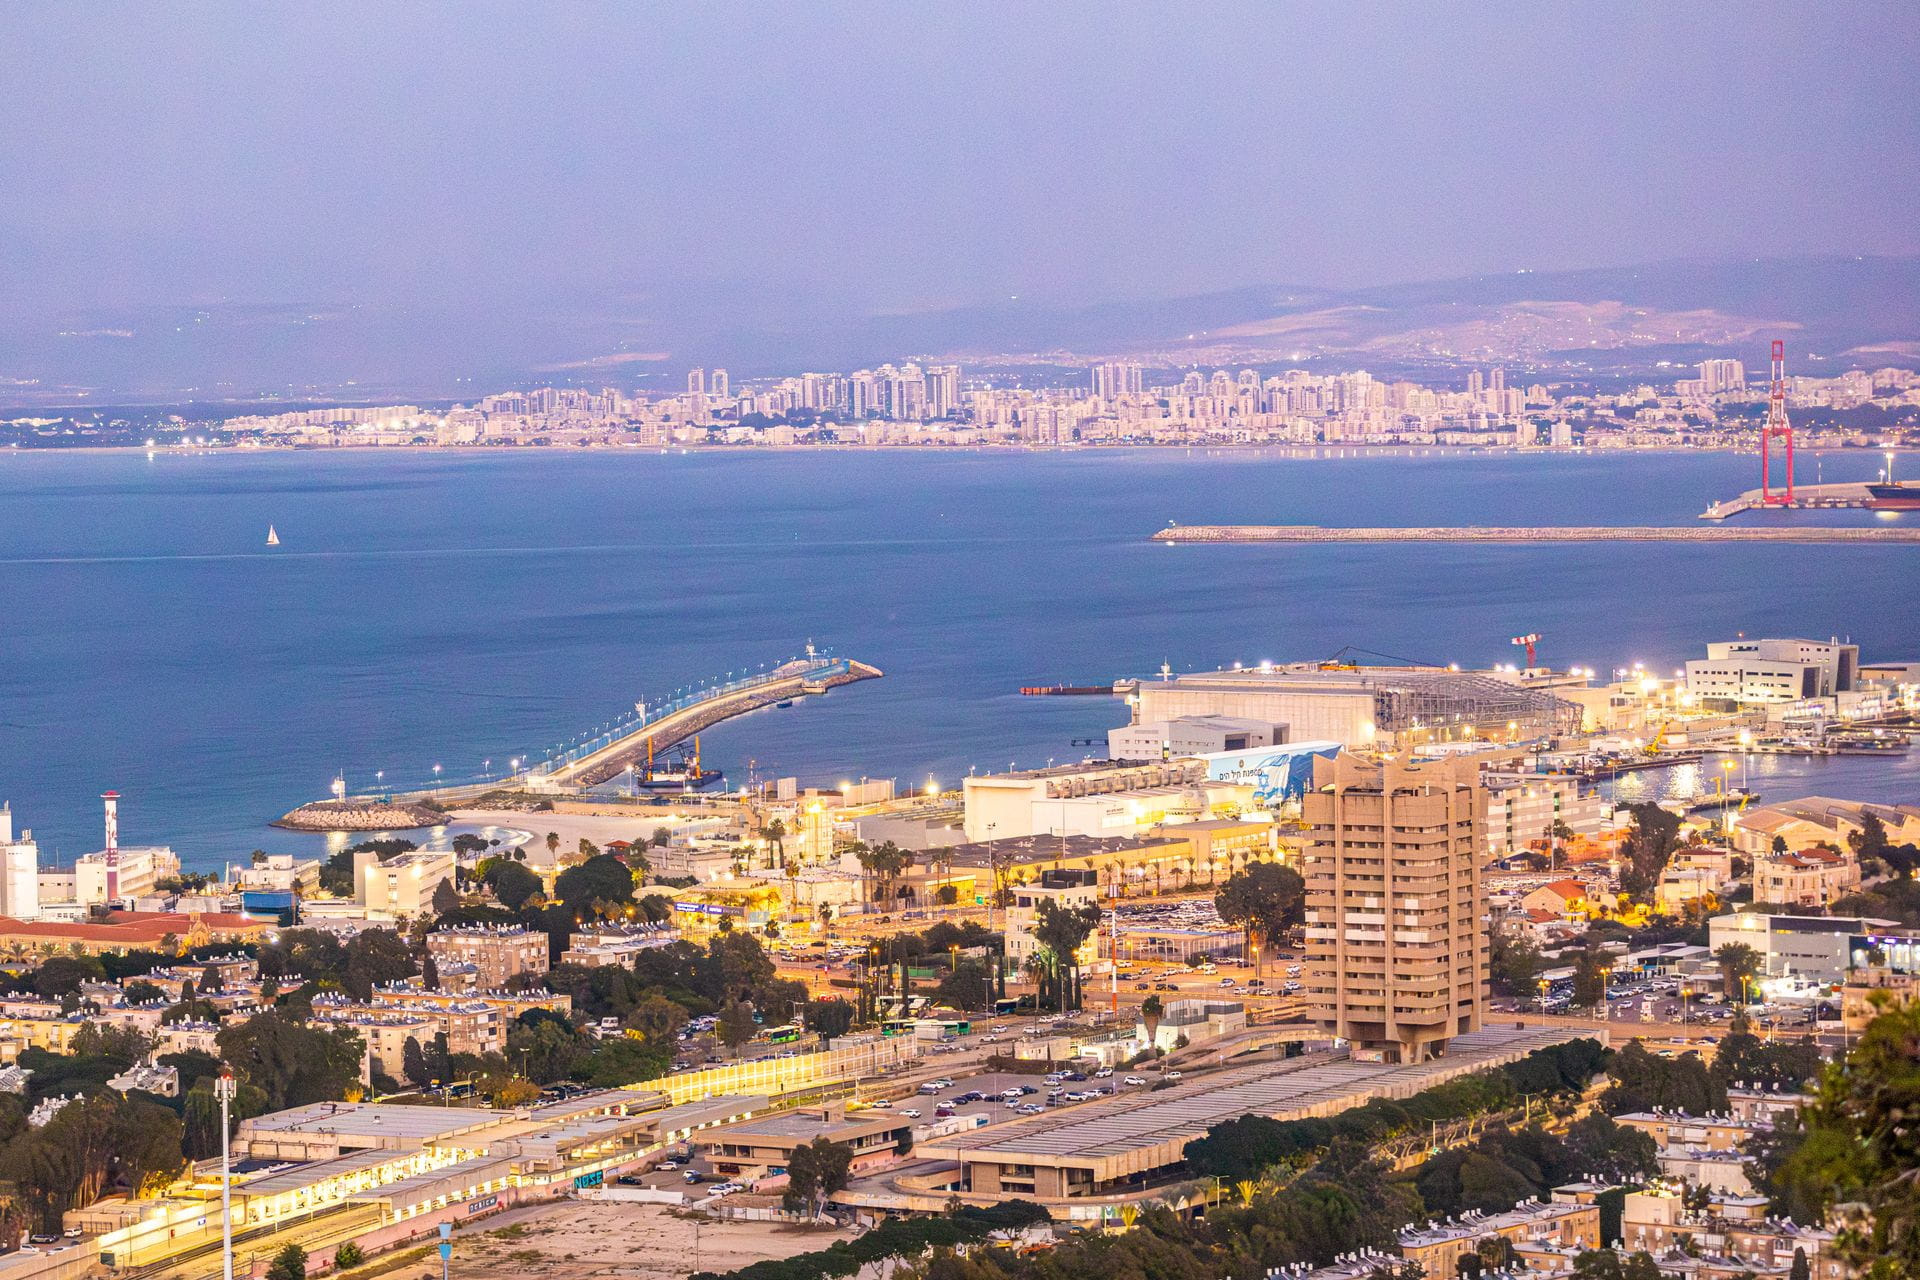
Israeli tourism benefits from a large domestic base that travels year-round. Weekend and holiday demand from local households cushions occupancy when inbound flights thin. Business travel into Tel Aviv adds midweek fill. Security events can cut international arrivals sharply, yet the domestic segment frequently rebounds first. Supply growth has been more measured in established coastal zones because land is scarce and planning processes take time. New short-stay stock still appears, especially in converted residential buildings, so owners must track registration data carefully.
Policy and planning context comes from the Israel Ministry of Construction and Housing, whose zoning and urban renewal programs influence how quickly hospitality stock can expand. Parallel reading of Bank of Israel monetary reports helps gauge borrowing costs that affect both new development and refinancing of existing hotels. Macro stability indicators published by the IMF Israel country analysis and comparative tourism statistics from the OECD round out the external picture without requiring proprietary research.
Seasonality Gaps That Create Rotation Windows
Greek islands experience sharp summer peaks and quieter winters. Israeli coastal cities show flatter calendars with religious holidays and school vacations creating multiple mini-peaks. When Greek summer rates are exceptionally high, owners sometimes lock in gains by selling or refinancing and then park capital in Israeli assets that generate steadier cash flow. Conversely, after a soft Israeli summer caused by temporary flight reductions, Greek inventory can look relatively expensive, prompting the opposite move.
These windows last only a few quarters. The scorecard therefore needs a seasonal adjustment factor so that summer-to-summer or winter-to-winter comparisons remain valid. Without that adjustment, temporary weather or calendar effects can be mistaken for structural shifts.
Currency, Airlift, and Policy Levers on the Card
A stronger euro can make Greek holidays costlier for shekel-based travelers and vice versa. Airline capacity into Athens, Thessaloniki, Tel Aviv, and regional Israeli airports changes the effective size of the market almost overnight. Bilateral tourism agreements and visa policies further influence who can travel freely. Each of these levers belongs on the scorecard as a qualitative overlay. A green occupancy score loses force if airlift is about to contract or if a new tax regime raises operating costs.
Owners who already hold Israeli real estate often ask how tourism assets interact with other strategies. Parallel approaches such as Agricultural Land Reclassification: An Underused Path to Outsized Returns or Haredi Family Housing Typologies: Modeling Approaches That Scale sit in different risk buckets yet compete for the same equity. Understanding relative returns helps decide whether tourism rotation is the highest use of capital this year.
Practical Ownership Moves Once the Scorecard Flashes Green or Red
When Greek supply overshoots demand, selective acquisition of well-located independent hotels at discounted valuations becomes feasible. When Israeli coastal occupancy stays firm while new supply remains limited, holding or expanding short-stay portfolios can compound cash flow. Refinancing tools such as the framework described in The BRRRR Method Applied to Israeli Real Estate: A Framework for Capital Efficie can free equity for the next rotation without full sale.
Luxury rental positioning also matters. Readers comparing Mediterranean gateways often study Dubai and Tel Aviv Luxury Rental Positioning: Forecast Inputs the Market Uses for signals that also apply to high-end tourism stock. Student and longer-stay housing can absorb capital when pure leisure softens; current lending conditions appear in Debt Terms for Student Housing Portfolios: 2026 Data and Macro Context. For broader reading, the Smart Strategies archive and the main Blog collect related analyses, while the FAQ (frequently asked questions) answers common process questions for first-time cross-border owners.
Keeping the Scorecard Honest Over Multiple Cycles
No single metric stays decisive forever. Greek recovery may mature into oversupply; Israeli domestic resilience may face new constraints. Update the card every quarter, archive previous versions, and note which assumptions proved wrong. Over time the exercise trains judgment better than any static forecast. Owners who treat the scorecard as a living tool rather than a one-time report will spot rotation opportunities earlier and avoid chasing last year’s winners.
Foundation publishes these frameworks so non-experts can participate in capital decisions that once belonged only to large funds. Clear supply and demand reading, honest scoring, and willingness to rotate when the numbers change remain the durable advantages.
Timeless Value. Perpetual Legacy.